
A recent market report from Additive Manufacturing Research estimates the current market for 3D printed drone components at $140 million in 2025, with projections reaching $900 million by 2034.
Titled “Additive Manufacturing Opportunities in Unmanned Aerial Systems 2026: Drones Market Analysis and Forecast,” the report breaks down the market by material, segment, application, geography, and vendor.
Additive Manufacturing Research identifies drone production as the top worldwide application for low-cost 3D printers making production parts, positioning it as the clearest case where AM has moved past its traditional role and into serial production. The reason comes down to economics.
Many tactical drones are designed to be field-deployable and, in some cases, single-use. That cost profile favors polymers and low-cost 3D printing over conventional manufacturing methods that require expensive tooling and longer setup times. When a product is expendable by design, the calculus around production methods shifts considerably.

Beyond Low-Cost Polymer Parts
Not all of the market runs on cheap polymer parts, though. Metal AM occupies a narrower but potentially consequential slice. According to the report, metal powder bed fusion (PBF) is the only class of 3D printing technology currently used in unmanned aerial systems production.
Penetration remains low, but the report flags propulsion systems and structural components for large payload-capacity drones as areas where metal AM could expand. As drone platforms grow in size and mission complexity, the gap between current adoption and stated potential is one worth watching.
What is driving that growth in platform scale, and in drone production volumes more broadly, is defense spending. AM Research attributes the rapid scaling of tactical military drone output to what governments worldwide now treat as a matter of national defense readiness.
The report argues that the speed at which nations feel compelled to develop both drone and counter-drone capabilities works in AM’s favor because conventional manufacturing requires longer lead times to establish production lines. AM can compress the timeline from design to production, which becomes a competitive advantage when urgency is the defining constraint.
The vendor landscape the report surveys reflects that urgency across both sides of the supply chain. On the 3D printing side, companies referenced include Stratasys, EOS, HP, Markforged, Nikon SLM Solutions, and Prusa Research.
The report names DJI, Skydio, General Atomics, Firestorm Labs, Titan Dynamics, and Quantum Systems, among others on the drone and defense end. The range of companies listed, from established defense contractors like General Atomics to leaner firms like Wild Hornets and Thyra, suggests a market that is fragmenting across incumbents and newer entrants instead of consolidating around a handful of dominant players.
Field Production Puts AM to Work
The report’s defense thesis already has evidence behind it on the ground. Last year, soldiers from the US Army’s 173rd Airborne Brigade were 3D printing FPV drones in the field at $400 to $500 each.
For comparison, the US Department of Defense’s (DoD) FY2026 missile procurement budget prices the Switchblade 600 loitering munition at $170,000 per unit. Soldiers can build a drone in just a few hours, a field-based manufacturing approach that emerged after the Army retired its RQ-7B Shadow drones in March 2024.
The distance between those two price points illustrates why the Additive Manufacturing Research report’s emphasis on cost-sensitivity and field-deployability as adoption drivers is not theoretical. It also suggests that AM’s strongest economic case lies in expendable tactical platforms, where low costs and rapid production can outweigh conventional manufacturing’s advantages.
Procurement contracts are starting to underwrite that shift at scale. Firestorm Labs raised $47 million to expand its xCell deployable microfactory, which enables 3D printed modular drone airframes at the point of need, and separately secured a $100 million US Air Force contract to lead development of 3D printed UAV solutions.
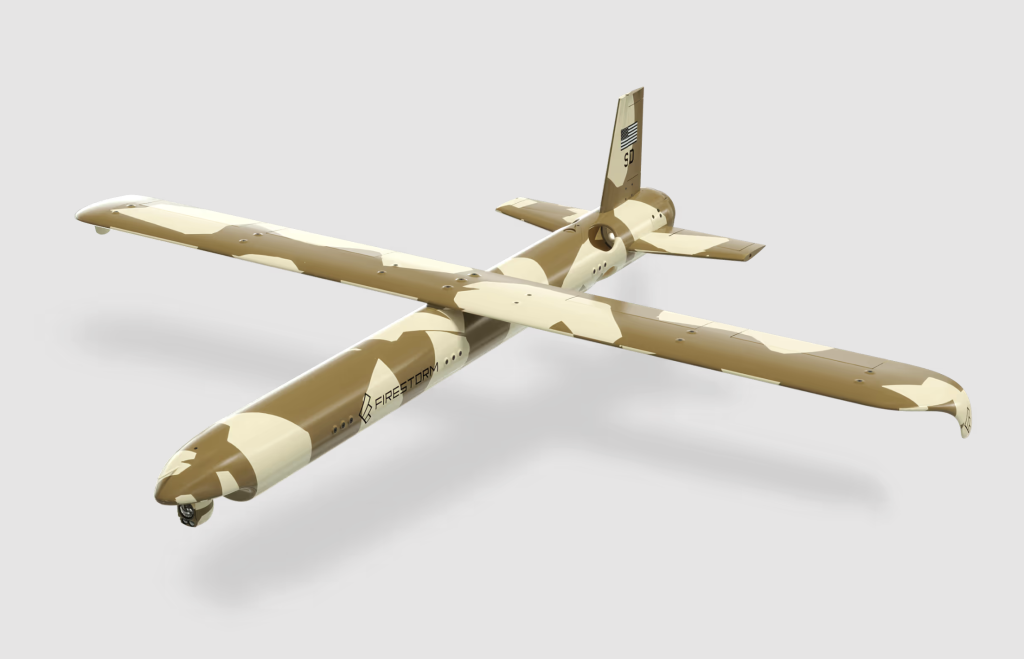
That kind of investment goes beyond standalone prototyping capability, funding deployable production infrastructure built around AM from the start. This reinforces the report’s underlying argument that defense urgency is compressing the timeline between AM adoption and volume manufacturing in ways that other industries have not yet experienced.
That roughly sixfold increase over nine years is a meaningful growth trajectory, but the real signal in this report may not be the top-line number. It is the claim that drones have become the number one application where low-cost 3D printers are producing production parts.
If that ranking holds, the drone sector could end up serving as the proof point for how AM finds its way into volume production, with adoption gaining ground first in product categories where the economics make traditional tooling less attractive.
3D Printing Industry is inviting speakers for its 2026 Additive Manufacturing Applications (AMA) series, covering Energy, Healthcare, Automotive and Mobility, Aerospace, Space and Defense, and Software. Each online event focuses on real production deployments, qualification, and supply chain integration. Practitioners interested in contributing can complete the call for speakers form here.
To stay up to date with the latest 3D printing news, don’t forget to subscribe to the 3D Printing Industry newsletter or follow us on LinkedIn.
Explore the full Future of 3D Printing and Executive Survey series from 3D Printing Industry, featuring perspectives from CEOs, engineers, and industry leaders on the industrialization of additive manufacturing, 3D printing industry trends 2026, qualification, supply chains, and additive manufacturing industry analysis.
Featured image shows Army Sgt. Tucker Smith solders internal wiring on a 3D printed FPV drone. Photo via Army National Guard Sgt. 1st Class Brittany Conley.