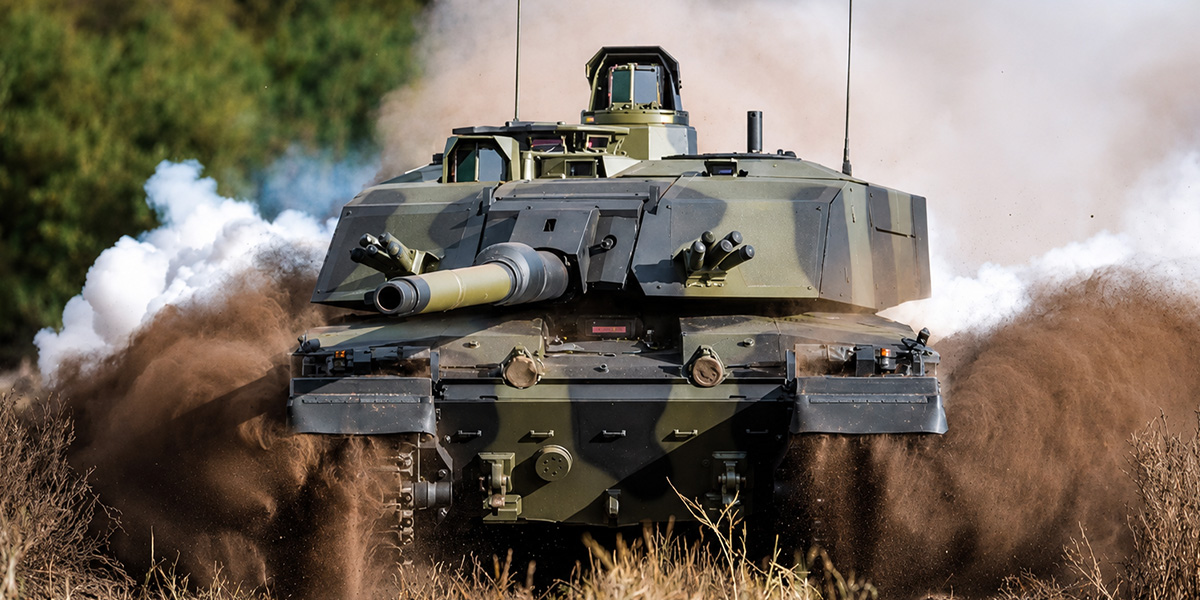
Rheinmetall UK, a primary land defense contractor for the British Army, has formalized additive manufacturing as its baseline production method for air ducting components within the Challenger 3 Main Battle Tank program.
The decision, detailed in a case study authored by Julian Wright, Technology Programmes Manager – Rheinmetall BAE Systems Land, marks a shift from conventional fabrication toward on-demand, in-house polymer printing, with broader implications for how sovereign defense manufacturers manage complex upgrade programs.
Conventional Ducting No Longer Fits
The Challenger 3 program presented a familiar but acute problem: the vehicle’s existing architecture left little room to maneuver. Ducting for the Crew Temperature Control System had historically been assembled from flexible tubing and sheet metal junction boxes, a proven, low-cost approach that simply couldn’t be adapted to the tighter spatial constraints of a tank upgrade.
Alternative manufacturing routes were evaluated. Injection molding and rotational molding can produce complex geometries, but both demand upfront tooling investment that becomes a liability when designs change, a near certainty in vehicle development, where subsystems compete for the same envelope throughout the program cycle. Tooling scrapped mid-program carries both financial and schedule risk. Additive manufacturing removed that variable entirely.
Choosing the Right Process: A Three-Way Trade
The team examined SLA, SLS, and FFF, each with genuine claims on the application.
Material qualification narrowed the field first. Ducting inside a combat vehicle must meet strict requirements for flame retardance, low smoke generation, and low toxicity, with a wide operating temperature range. SLA was ruled out early for lack of qualifying material. SLS offered PA2241FR as a candidate, but the UK supply chain for that material was found to be uncompetitive, and the process itself carries higher capital expenditure and more complex shop floor integration than the program could justify at the required volumes.

FFF with ULTEM 9085 met the material specification. The process also aligned with Rheinmetall UK’s existing knowledge base, the team had used desktop FFF extensively for prototyping, meaning the cultural and training burden of moving to production-grade FFF was manageable. The residual weaknesses of the process, notably surface finish and air permeability, were addressed through vibratory tumbling and painting, adding modest cost without requiring additional capital equipment.
The decision to manufacture in-house rather than contract out was equally deliberate. The available supply chain lacked the cyber security accreditation, Cyber Essentials+, required for a defense program, and external production would have reduced the team’s ability to iterate quickly and accumulate process knowledge.
The miniFactory Ignite: A Considered Selection
Several high-temperature FFF platform providers were assessed before Rheinmetall UK settled on the miniFactory Ignite. The Finnish-manufactured machine offered a large build volume at a price point below comparable systems, enabling batch production and reducing the labor overhead associated with managing individual builds. The open-material architecture allowed feedstock to be purchased directly from the material manufacturer, with a significant effect on piece-part cost.
Security was a factor. Finnish manufacturing origin was considered lower cyber risk relative to some competing platforms, a consideration that carries weight in a program of this classification. UK-based technical support, delivered through reseller 3DGBIRE from a location a few hours from Rheinmetall UK’s Telford facility, addressed the machine downtime risk that could otherwise translate into program delay.
Reusable build plates, long-lasting nozzles, and a lower consumables burden kept the total cost of ownership in line with program expectations.
Outcomes and What Comes Next
Once the machine was operational, the team found that splitting components and introducing joints reduced or eliminated the need for support material, cutting print time, material consumption, and post-processing hours. The result was a single-machine production flow that met the program’s capacity requirements.
The operational benefits were tangible. Design changes that previously required weeks of supplier lead time can now yield a replacement part within a day. On-demand production removes the need for advance procurement and buffer stock, while the absence of tooling means no capital investment is written off when a drawing is revised. Components damaged during fitting are reprinted on site rather than re-entered into a procurement cycle.
Rheinmetall explained that the Challenger 3 experience has accelerated the company’s wider adoption of additive manufacturing. Following the polymer work with the miniFactory, the company has since invested in Rapidia‘s Metal Paste Deposition technology for steel vehicle components, signal that the program served as proof of concept for a broader manufacturing shift.

Sovereign Capability and the Defense AM Imperative
Rheinmetall UK’s decision to keep production on its own shop floor rather than hand it to a supplier reflects a strategic approach now visible across defense programs in multiple countries. The UK Ministry of Defence has backed exactly this model at the program level: Rolls-Royce opened a dedicated 350 m² Additive Manufacturing Development Cell in Bristol, purpose-built, government-funded, and tied directly to next-generation military aircraft engine production. The facility uses metal powder bed fusion under tightly controlled environmental conditions, applying the same principle Rheinmetall UK applied with FFF: bring the capability in-house, control the process, and build the knowledge base where the program actually runs.
The same strategic approach is playing out in the United States. Hadrian launched Hadrian Additive, a new division focused on delivering production-ready, scalable additive manufacturing to the U.S. defense sector and allied partners. This move integrates additive capabilities directly into Hadrian’s factory ecosystem, allowing critical defense programs to move from validated designs to full-scale production efficiently.
The broader industry trajectory is consistent. Where programs once tolerated additive manufacturing as a prototyping convenience, they are now structuring production around it.
3D Printing Industry is inviting speakers for its 2026 Additive Manufacturing Applications (AMA) series, covering Energy, Healthcare, Automotive and Mobility, Aerospace, Space and Defense, and Software. Each online event focuses on real production deployments, qualification, and supply chain integration. Practitioners interested in contributing can complete the call for speakers form here.
To stay up to date with the latest 3D printing news, don’t forget to subscribe to the 3D Printing Industry newsletter or follow us on LinkedIn.
Explore the full Future of 3D Printing and Executive Survey series from 3D Printing Industry, featuring perspectives from CEOs, engineers, and industry leaders on the industrialization of additive manufacturing, 3D printing industry trends 2026, qualification, supply chains, and additive manufacturing industry analysis.
Featured image shows Rheinmetall UK Integrates FFF Into Challenger 3 Production. Photo via Rheinmetall UK.