Ahead of AMA: Energy 2026 on April 30th, 3DPI is turning the spotlight on the use of Additive Manufacturing in the energy sector. The additive manufacturing industry has spent years proving that 3D printing can move beyond prototyping into operational supply chains. For heavy industries, mining, energy, maritime, the case is becoming clearer, but the path from pilot project to scaled adoption remains one of the sector’s most persistent challenges.
Espen Siversten, CEO, Ivaldi Group, has spent eight years working with large industrial operators across key continents to understand where digital spare parts networks create real value and where they fall short. His conclusion: the technology is ready, but the business case infrastructure around it is not.
“We’ve analyzed 2.3 million parts and US$1.6 billion in annual spare parts spend,” Siversten explained. “On average, 3–11% are suitable for local manufacturing, depending on the industry. But suitability is only the starting point. The real gap is between knowing a part can be made differently and actually making it happen. That’s where Ivaldi comes in: guiding companies through a smooth, confident transition.”
From Inventory to On-Demand
The core proposition of digital spare parts is straightforward: instead of warehousing thousands of components at facilities around the world, operators send part data to a local manufacturer and produce what they need, when they need it. The model targets the twin costs of excess inventory and unplanned downtime, two expenses that weigh heavily on asset-intensive industries operating in remote locations.
What complicates the transition is that supply chains in heavy industry are not built for experimentation. A mine in South Africa, an offshore platform in Norway and a manufacturing facility in Germany each present different regulatory environments, logistics constraints and risk profiles. A value calculation that works in one context may not transfer to another, which means digital supply network strategies need to be built facility by facility, not applied uniformly across a portfolio.
Siversten identifies three dimensions that determine whether a digital spare parts approach makes sense for a given operator: the type of facility, the type of parts in use, and the strategic context, including local regulations, carbon obligations and geopolitical risk such as tariffs or supply chain disruption.
The Data Problem
One of the most consistent obstacles operators face is the absence of usable part data. For a mine that has been running for four years without a structured digital inventory, there is often little to work with when evaluating whether a component can be additively manufactured. The result is that procurement teams receive an answer of “it depends,” which, in practice, means sending field technicians back out to gather fitment measurements before any estimate can be produced.
To address this, the Ivaldi Group has developed a tiered capture process. A field technician with basic equipment can gather enough information for an initial estimate. If the operator decides to proceed, a certified specialist with more precise instruments can follow up. For parts requiring full material validation, components can be sent to a testing laboratory for CAD scanning and full analysis. The goal is to compress the time between inquiry and actionable quotation without compromising quality at each stage.
The same logic applies to certification. Part families certification, now being introduced for the offshore and maritime sectors, allows a category of components to be pre-certified, so that individual parts meeting those specifications can be cleared for production within 24 hours. For downtime-sensitive equipment, that turnaround time can directly determine whether an asset stays operational or goes offline.
“DART is our context engine. It connects part families, historical procurement, risk and cost models, CO₂ impact, and downtime metrics, turning limited inputs into context-rich decisions,” said Siversten.

Making the Business Case
The adoption barrier in heavy industry is not primarily technical, it is financial and organizational. Maintenance teams measure performance in unscheduled downtime events. Procurement teams measure cost per part. Finance leadership measures return on capital. Each layer of a large industrial organization applies a different lens, and a digital spare parts proposal needs to speak to all of them.
Equinor, widely cited as the leading adopter in the European energy sector, has publicly reported savings of over US$100 million from additive manufacturing programs, built largely by embedding production capability directly at the sites where demand originates, rather than running isolated pilot programs.
The broader industry, however, is still working through what Siversten calls “death by pilots”: programs that generate promising early results but fail to scale because the business case cannot survive contact with a finance committee.
Closing that gap requires better data infrastructure, faster quoting tools, pre-certified part families, and a shared industry taxonomy so that operators, manufacturers, and regulators are working from the same definitions. Siversten explained that initiatives such as the AM Energy network, established with participation from operators, manufacturers, and regulators, are moving in that direction, building standards, playbooks, and an open platform for the industry to coordinate around.
“The parts are there. The demand is there. The remaining work is making the economics legible enough that the decision to switch becomes straightforward,” said Siversten.
Spare parts supply chains: a risk hiding in plain sight
Traditional spare parts strategies were built for a stable world. Conflict, climate disruption, shipping bottlenecks, and geopolitical tension have turned long, centralized supply chains into liabilities, and the financial exposure is concrete. Energy companies alone lose an estimated US$30 billion annually due to ineffective inventory management.
The industry response is moving from reactive to structural. With rising protectionism and supply chain shocks pushing governments and OEMs to localize production, on-demand, locally produced spare parts are emerging as the most practical hedge and several companies are already acting on it.
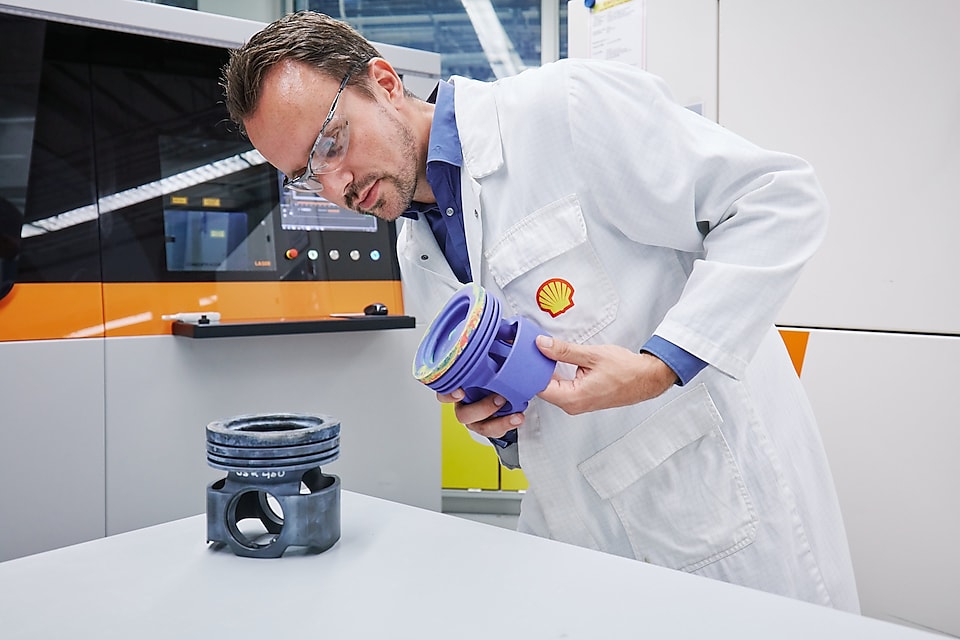
For instance, Shell has used 3D printing to cut manufacturing costs by 90% on offshore components, and is building a certified database of digital part passports to enable on-demand production, directly reducing physical stock, lead times, and warehousing costs.
Elsewhere, Immensa and DNV launched what they call the world’s first global guideline on digitizing spare parts, with an AI process capable of assessing 500,000 parts in 24 hours. Vestas and Würth Additive Group have moved beyond pilot projects to embed additive manufacturing directly into their operational supply chains, with digital inventory and parts standardization becoming central to how they manage supply risk.
Ivaldi sits at exactly this inflection point, giving companies the data, context, and guided process to convert spare parts vulnerability into a manageable, measurable risk.
Register for AMA: Energy 2026, our free online event on April 30th.
3D Printing Industry is inviting speakers for its 2026 Additive Manufacturing Applications (AMA) series, covering Energy, Healthcare, Automotive and Mobility, Aerospace, Space and Defense, and Software. Each online event focuses on real production deployments, qualification, and supply chain integration. Practitioners interested in contributing can complete the call for speakers form here.
To stay up to date with the latest 3D printing news, don’t forget to subscribe to the 3D Printing Industry newsletter or follow us on LinkedIn.
Explore the full Future of 3D Printing and Executive Surveyseries from 3D Printing Industry, featuring perspectives from CEOs, engineers, and industry leaders on the industrialization of additive manufacturing, 3D printing industry trends 2026, qualification, supply chains, and additive manufacturing industry analysis.