3D printer OEM Stratasys (Nasdaq: SSYS) announced its financial results for the second quarter (Q2) of 2026.
Revenue for the quarter was $137.6 million, down 0.3% Y/Y from $138.1 million and up 3.7% Q/Q from $132.7 million in the previous quarter. Higher Services revenue, driven primarily by on-demand parts production, largely offset the decline in Products revenue as longer sales cycles weighed on system purchases.
That top-line stability, however, came with some margin compression. Gross profit fell to $58.2 million, down 2.1% Y/Y, while GAAP gross margin declined to 42.3% from 43.1% a year earlier. The company attributed pressure on profitability primarily to currency headwinds from the stronger Israeli shekel.
Below gross profit, cost discipline helped narrow the gap. The operating loss improved to $13.5 million from $16.6 million in Q2 2025, as operating expenses declined by $4.4 million and more than offset the $1.3 million reduction in gross profit. Adjusted EBITDA was $5.3 million, compared with $6.1 million a year earlier, with management citing a $2.9 million adverse impact from the stronger Israeli shekel.
Net loss, though, remained largely unchanged at $16.9 million versus $16.7 million in the prior-year quarter. The improvement in operating loss and the absence of losses from associated companies were largely offset by higher income tax expense.

Products and services show mixed performance
The divergence in the top line becomes clearer at the segment level. Product revenue declined to $92.7 million, down 2.2% Y/Y, while Services revenue increased to $44.9 million, up 3.6% Y/Y.
Within Products, the picture was similarly split. Consumables revenue reached a quarterly record of $66.3 million, up 3.3% Y/Y, driven by increased utilization of manufacturing materials for end-use production.
System revenue, meanwhile, fell 13.7% Y/Y to $26.4 million as customers faced longer sales cycles and capital expenditure pressure. Management said the company continues to see a robust pipeline of larger manufacturing opportunities and expects a notable improvement in system sales during the second half.
On the Services side, growth was primarily driven by on-demand parts production. Stratasys Direct Manufacturing (SDM) grew 12.1% Y/Y, fueled by demand from defense technology companies for drone and munitions production, while customer support revenue remained roughly flat.
| Revenue $ thousands | Q2 2026 (rounded) | Q2 2025 (rounded) | Variance $ thousands | % |
| Products | $92.7M | $94.8M | -$2.0M | -2.2% |
| Services | $44.9M | $43.3M | +1.6M | +3.6% |
| Total revenue | $137.6M | $138.1M | -$0.4M | -0.3% |
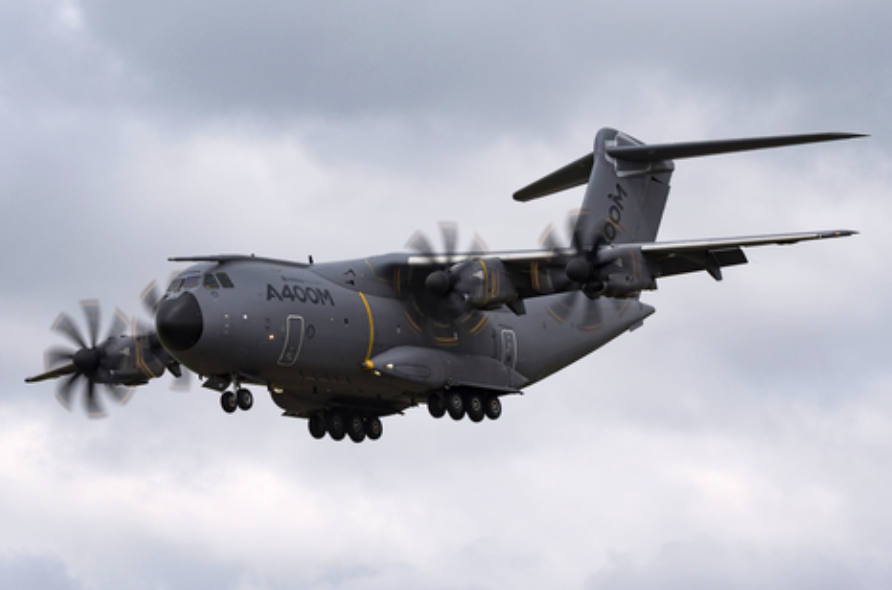
Much of that services momentum came from aerospace and defense, which expanded during the quarter with support from deeper-level sustainment and spare-parts production for the US Air Force. Stratasys Direct produced more than 12,000 aerospace and defense parts during the quarter, primarily for drone and munitions applications, and recorded its highest backlog to date.
Beyond defense, the company highlighted several production-focused customer programs. FANUC adopted Stratasys industrial solutions into its supply chain, while FAW is using Stratasys systems to produce interior end-use components.
Stratasys is also investing in production-readiness infrastructure. The company secured a $7.8 million program with America Makes to develop in-situ monitoring hardware and software for the F900 and a future F3300 technology refresh, focused on production, sustainment and supply-chain applications across the defense sector.
Alongside organic investment, the company is preparing to broaden its technology portfolio through the planned acquisition of Markforged from Nano Dimension in an all-cash deal worth $42.5 million. The transaction, expected to close later in 2026, would bring Markforged’s continuous carbon fiber technology platform and its Digital Forge software suite, which integrates hardware, materials and print-management tools.
Markforged generated approximately $70 million in revenue in 2025, although that figure includes its Metal Binder Jetting product line, which Nano Dimension is retaining. Management also highlighted simulation and remote print-management software capabilities alongside the acquisition.
Stratasys maintains 2026 revenue outlook
Stratasys reaffirmed its 2026 revenue outlook between $565 million to $575 million, continuing to expect sequential revenue growth across all four quarters. Management expects system sales to improve in the second half as larger manufacturing opportunities progress, although the timing of these deals is expected to create quarter-to-quarter variability.
On cash flow, the outlook has shifted. The company no longer expects full-year operating cash flow to be positive following high, non-routine legal expenses related to protecting its IP portfolio incurred during the first half. Stratasys nevertheless expects operating cash flow to turn positive in the second half.
Looking ahead, management expects continued expansion of production-focused business, with the pipeline growing particularly across aerospace and defense. A&D, dental and Stratasys Direct were identified as areas supporting structural demand.
Register now for AMA: Software 2026. Join 3D Printing Industry on 22 October for expert presentations, panel discussions and live audience Q&A exploring the software shaping additive manufacturing. Register here.
To stay up to date with the latest 3D printing news, don’t forget to subscribe to the 3D Printing Industry newsletter or follow us on LinkedIn.
Explore the full Future of 3D Printing and Executive Survey series from 3D Printing Industry, featuring perspectives from CEOs, engineers, and industry leaders on the industrialization of additive manufacturing, 3D printing industry trends 2026, qualification, supply chains, and additive manufacturing industry analysis.
Featured image shows Stratasys technology in the aerospace and defense sectors. Photo via Stratasys.