
The 3D Printing Industry Year in Review continues with the biggest stories from February.
After January’s volatility, the month brought sharper definition to where demand held, where capital hesitated, and where governance began to matter as much as technology. Defense procurement hardened into the most reliable demand signal, capital flows became selective rather than expansive, and legal and software control issues moved from background risk to operational reality.
AI shifted from aspirational narrative toward embedded tooling, while construction AM progressed along the path from demonstration into compliance-driven procurement. Rather than accelerating, the industry recalibrated. Put simply, February made clear the conditions under which AM would operate.
Sentiment narrows, priorities harden
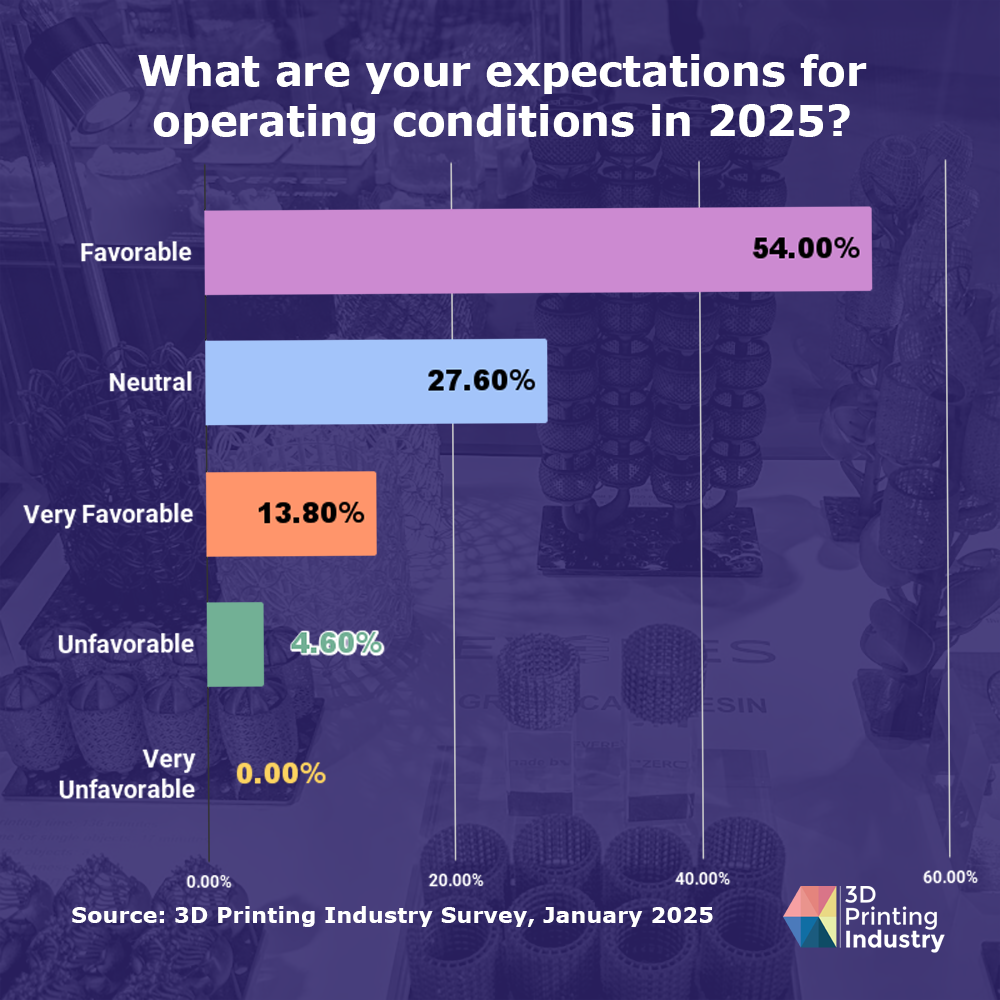
February’s framing came from our 3DPI Executive Survey economic outlook, which offered a restrained but informative snapshot of industry conditions. Executive sentiment remained net positive, yet the distance between 2024 forecasts and actual outcomes exposed persistent demand weakness, particularly for capital-intensive systems.
Business conditions improved, but not to the extent anticipated, while operating conditions revealed unexpected friction. The signal was not collapse, but recalibration. Additive manufacturing advanced unevenly, with confidence concentrated in specific applications rather than across the market.
Within that context, executive priorities narrowed. Defense, healthcare, aerospace, and energy continued to stand out as defensible segments, supported by qualification requirements, long program lifecycles, and regulatory complexity. Software, automation, and workflow integration appeared just as central to executive planning as hardware.
The 3D printing trends for 2025 reflected a shift away from expansion narratives toward operational discipline. Consolidation, litigation, and geopolitical pressure were not seen as mechanisms forcing clarity around viable business models and realistic deployment paths.
Meanwhile, our AI-focused survey translated February’s broader caution into operational terms. Executives consistently positioned AI as an efficiency tool rather than a creative one, emphasizing process monitoring, design automation, simulation, qualification, and predictive maintenance.
The value proposition was time saved, errors avoided, and throughput stabilized, particularly in production and fleet-level environments. Skepticism toward hype coexisted with practical adoption, reinforcing the sense that AI was being absorbed into manufacturing infrastructure rather than treated as a disruptive overlay.
In February, AI’s impact on additive manufacturing did not signal acceleration; it signaled standardization.
Defense demand crystallizes
This month, defense emerged as the most coherent demand signal for additive manufacturing.
The USAF investment in 3D printed UAS and the 3D printed loitering munition US Army trials placed additively manufactured systems squarely within formal evaluation and procurement pathways. In both cases, AM was treated as an enabler of modularity, cost control, and rapid deployment in contested environments, instead of an experimental manufacturing approach.
That same logic also extended to maintenance and training environments. The integration of Bambu Lab 3D printers for drone maintenance at Creech Air Force Base addressed spare part shortages, cost pressures, and training delays rather than novelty or innovation optics.
The choice of commercially available desktop systems effectively collapsed the boundary between consumer and military supply chains. Speed, availability, and point-of-need fabrication mattered more than platform pedigree.
Materials strategy completed the picture across defense supply and production planning. Supernova Industries’ 3D printing energetic materials defense contract showed AM being pushed into tightly regulated, higher-risk domains where consistency and safety are critical.
Meanwhile, Rolls-Royce’s RAF jet recycling into 3D printing material and IperionX’s DoD titanium supply chain contract reflected a systemic defense focus on material sovereignty, circularity, and domestic resilience. Across these developments, defense buyers showed little concern for AM ideology. Their priorities were speed, supply security, and deployability.

Funding with conditions attached
The month also saw capital still flowing into AM, but in a far more selective and conditional form. The Stratasys $120 million Fortissimo investment provided balance sheet reinforcement at a premium valuation, yet it landing alongside Stratasys preliminary Q4 2024 results underscored ongoing pressure on capital equipment demand and continued operating losses under GAAP measures.
The timing mattered because the investment strengthened liquidity and governance alignment, but it did not resolve structural questions around profitability, nor did it insulate the company from legacy acquisition risk tied to earlier growth strategies.
Those risks were made explicit by the ongoing Origin earn-out litigation, which remained unresolved as the court weighed arbitration vs. trial. The dispute highlighted how acquisition-era deal structures continue to surface as liabilities.
A similar reckoning was visible through Nano Dimension CEO shareholder letter amounting to a public reset. The company acknowledged that consolidation without operational clarity, disciplined capital allocation, or investor trust had failed to deliver value, despite significant capital raised during peak market enthusiasm. Governance reform, expense control, and potential restructuring replaced expansion-driven narratives.
By contrast, the ICON $56 million Series C funding stood apart, not because it contradicted the trend, but because it fit a narrower investor narrative. Construction 3D printing continued to attract capital where scale, public infrastructure, and government partnerships remained legible, including defense and space. Even here, funding followed layoffs and a tighter focus on deployable systems rather than broad experimentation.
Capital activity this time around signaled repricing rather than retreat, with capital available but no longer patient, narrative-driven, or tolerant of ambiguity.
Control layers move upfront
February surfaced law, IP, and platform control as first-order industry constraints rather than background noise.
The Origin shareholders lawsuit against Stratasys and the Continuous Composites lawsuit after Markforged dispute reflected post-acquisition and post-litigation cleanup, where earn-outs, contingency structures, and arbitration clauses were being actively contested rather than quietly settled. These cases pointed to a maturing sector in which financial engineering from the last cycle was being stress-tested in court.
At the platform level, Stratasys vs Bambu Lab lawsuit update underscored how control over distribution, hardware features, and IP had become a competitive lever. The dispute was not only about alleged infringement but about jurisdiction, subsidiary responsibility, and who constitutes a primary participant in a global hardware business. This highlighted that IP enforcement was now being used to define market boundaries as low-cost desktop systems scaled rapidly.
Software control sharpened this dynamic further. Bambu Lab’s firmware changes and Orca Slicer rejecting Bambu Connect exposed growing tension between security-driven platform consolidation and ecosystem trust rooted in open tooling.
Together, these episodes suggested that competition in AM was no longer confined to machines or materials. Control over software, users, and integration pathways had become a constraint that companies now had to manage as carefully as cost or performance.
Software infrastructure beats novelty
Software announcements reinforced that compute and workflow infrastructure, is where AM investment remains defensible.
One notable example was the Authentise Autodesk additive manufacturing collaboration functioning as consolidation rather than expansion.
Design validation, slicing, nesting, scheduling, and execution were unified within a single, version-controlled production environment. In a weak demand cycle, continuity of data and governance across design and production outweighed incremental feature additions.
Additionally, the nTop acquisition to accelerate CFD pointed in the same direction. By embedding GPU-native fluid simulation into its computational design platform, nTop reduced iteration time in aerospace and turbomachinery, where simulation fidelity underpins qualification and performance claims.
Removing meshing and accelerating solver speeds targeted a known workflow bottleneck rather than expanding product scope. Earlier integrations with Nvidia reinforced compute efficiency as a prerequisite for credible design automation.
These moves aligned closely with February’s AI discussion. Intelligence mattered only when embedded in production software, simulation, and process control, not as standalone tools. As certification pressure and cost sensitivity increased, software that reduced friction between design, simulation, and execution shifted from optional capability to enabling infrastructure.
Construction meets procurement reality
Finally, February showed construction 3D printing moving decisively from demonstration to procurement. ICON’s $56 million raise mattered less as a capital event than as reinforcement of a model already validated by institutional buyers, most clearly the U.S. Department of Defense (DoD).
The 3D printed barracks at Fort Bliss framed construction AM as compliant military infrastructure, constructed in accordance with the DoD’s updated Unified Facilities Criteria, which now formally include AM methods.
In this context, funding followed proof of deployability rather than vision alone. Governments appeared as early customers, signaling that scale, repeatability, and compliance had overtaken novelty as the conditions under which construction AM now advanced.

Lessons from February
By the end of the month, February reframed AM as an industry adjusting to limits rather than chasing possibility. Institutional buyers set the pace, capital demanded discipline, and legal, software, and data control emerged as competitive constraints.
The month’s events showed AM becoming more legible and less forgiving, with fewer narratives tolerated and fewer shortcuts available. Progress was defined by deployability, compliance, and integration rather than novelty or scale promises. In this sense, February did not signal contraction, but maturation.
Read more in our series looking at the 3D printing news for 2025, plus how did additive manufacturing expert forecasts match the reality of the year?
3D Printing Forecasts vs Reality 2025
Additive Manufacturing in 2025 Executive Summary – Part One
Additive Manufacturing in 2025 Executive Summary – Part Two
3D Printing Industry Review of the Year January 2025
3D Printing Industry Review of the Year February 2025
3D Printing Industry Review of the Year March 2025
3D Printing Industry Review of the Year April 2025
3D Printing Industry Review of the Year May 2025
3D Printing Industry Review of the Year June 2025
3D Printing Industry Review of the Year July 2025
3D Printing Industry Review of the Year August 2025
3D Printing Industry Review of the Year September 2025
3D Printing Industry Review of the Year October 2025
3D Printing Industry Review of the Year November 2025
3D Printing Industry Review of the Year December 2025
The 3D Printing Industry Awards are back. Make your nominations now.
Do you operate a 3D printing start-up? Reach readers, potential investors, and customers with the 3D Printing Industry Start-up of Year competition.
To stay up to date with the latest 3D printing news, don’t forget to subscribe to the 3D Printing Industry newsletter or follow us on LinkedIn.
While you’re here, why not subscribe to our Youtube channel? Featuring discussion, debriefs, video shorts, and webinar replays.
Featured image shows a US solider launching a loitering munition. Photo via Sgt. Gregory T. Summers, 22nd Mobile Public Affairs Detachment/US Army.